IN Brief:
- Ford, General Motors, and JLR are among bidders for a £900 million UK military vehicle requirement initially covering about 3,000 vehicles.
- Automotive groups are adapting established platforms, engineering resources, and supply chains rather than creating entirely separate vehicle businesses.
- Underused automotive factories are also attracting defence manufacturers seeking industrial capacity without constructing new plants.
Western vehicle manufacturers are increasing their defence activity through modified commercial platforms and underused factory capacity, with Ford, General Motors, and JLR among the companies pursuing Britain’s next light military vehicle requirement.
The manufacturers are among bidders for a Ministry of Defence programme valued at about £900 million and initially covering around 3,000 vehicles. Instead of beginning with completely new military designs, the competing automotive groups are drawing on established platforms, engineering teams, suppliers, and production systems before adapting the vehicles around military mobility, payload, communications, and support requirements.
Ford’s proposal is based around the Ranger pickup and brings the automotive manufacturer together with General Dynamics Land Systems and Ricardo. General Motors is involved through GM Defense, while JLR is offering Defender Wolf Series II through its newly established Defender Defence Division. The approaches differ, but each uses an existing automotive engineering base as the starting point for a military product.
That provides an obvious industrial advantage. Commercial vehicle manufacturers already operate supply chains and production systems at volumes far above those normally required by a national military fleet. Engines, transmissions, electrical architectures, diagnostics, components, and manufacturing controls can therefore be drawn from established programmes rather than developed independently for a few thousand military vehicles.
The savings are not automatic. Military use can introduce different payloads, electrical loads, communications equipment, environmental requirements, electromagnetic compatibility limits, recovery arrangements, and support expectations. Manufacturers therefore have to preserve enough commonality with the commercial platform to retain its scale advantage while proving that the final configuration can withstand a substantially different operating environment.
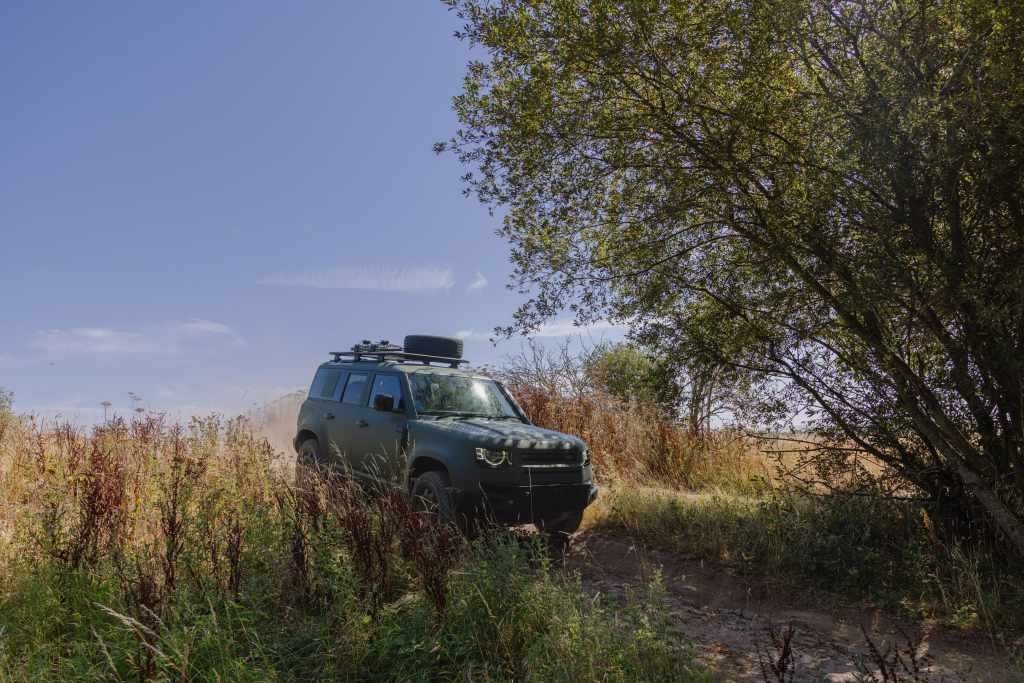
JLR’s Defender Wolf Series II illustrates that balance. The vehicle uses the company’s D7x monocoque architecture and is being offered in several military configurations, including tactical mobility and utility variants. JLR says the vehicle was designed and engineered in the UK, with key technology and engines also produced domestically, and that the underlying Defender architecture completed more than 62,000 engineering sign-off tests.
The military derivative removes equipment unnecessary to the role while retaining the structural and off-road engineering of the commercial Defender family. That is a different approach from taking a civilian showroom vehicle and adding military paint and radios. Payload distribution, attachment points, electrical integration, cooling, durability, and maintainability all affect whether a commercial architecture remains suitable once military equipment is fitted.
GM Defense provides another model because it already operates as a dedicated defence business inside a much larger automotive group. Its military vehicles draw extensively on General Motors components and engineering, giving the business access to commercial scale without requiring the parent company to redirect its mainstream assembly network towards low volume defence production.
That distinction helps explain why growing defence expenditure is attractive but cannot replace the passenger vehicle market for global manufacturers. A 3,000-vehicle military programme can provide valuable work to an engineering team or specialised assembly operation, yet remains modest beside factories designed to produce hundreds of thousands of civilian vehicles. Automakers are therefore treating defence as an additional market and a potential use for selected capacity rather than a substitute for weakening car sales.
Factory capacity provides a second route into the sector. Some of the clearest links between automotive and defence are emerging when established vehicle plants become available to defence manufacturers that already have programmes but need more production space. That can be more practical than forcing military products onto an active mass production line whose equipment, takt times, workforce structure, and supply chain were designed around civilian vehicles.
Automotive suppliers provide a similar opportunity at a smaller scale. Machining, casting, moulding, fabrication, electronics, and testing businesses often have equipment directly relevant to defence manufacturing, but qualification, traceability, security, and customer approval can slow entry. Spare capacity therefore matters only when the supplier can demonstrate the controls required by the defence programme.
British suppliers have already been examining how automotive production skills can be applied to defence work, while factory transfer proposals elsewhere in Europe and North America show the same industrial logic at site level. Existing buildings, utilities, trained staff, and transport links can shorten the time required to establish capacity, although the manufacturing process still has to be reconfigured and qualified for the new product.
The UK light mobility competition will provide a useful test of the platform approach. Established defence vehicle manufacturers bring military integration experience, while the automotive entrants bring scale, mature commercial hardware, and extensive supplier networks. Contract award will show how the Ministry of Defence balances those attributes against protection, mobility, support, and through life requirements.
The wider movement is already more nuanced than a simple conversion of car factories into arms plants. Automotive groups are identifying targeted military uses for existing platforms and engineering resources, while defence manufacturers are examining automotive sites and suppliers where capacity can be transferred economically. The opportunity lies in the overlap between the sectors; the engineering standards and production economics remain distinctly different.