IN Brief:
- The Netherlands is preparing European origin requirements for critical defence super fibres.
- The measures may extend to existing contracts where legal and commercial conditions permit.
- A study on protecting and scaling European production is expected in early 2027.
The Netherlands is preparing to use procurement policy to reduce defence dependence on non-European super fibres, including the possibility of applying European origin requirements to existing contracts where legal and commercial conditions allow.
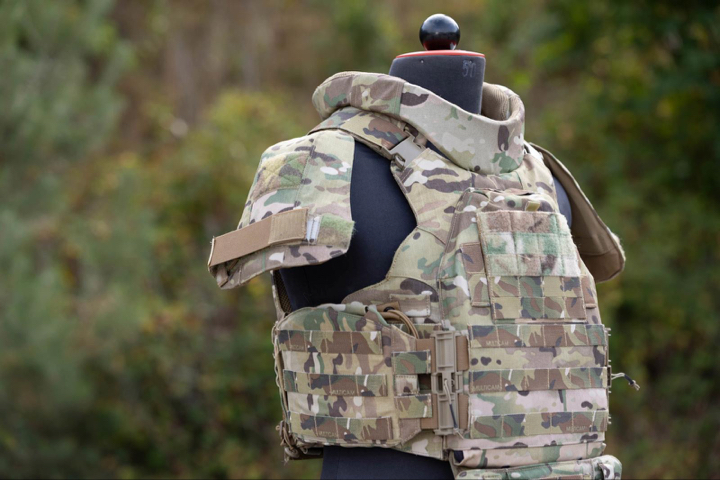
The Netherlands Ministry of Defence says the materials are critical to military equipment including helmets, fragmentation protection, vehicles, and aircraft. Its concern is not limited to the availability of finished products: the ministry is also seeking to preserve sufficient Dutch and European fibre manufacturing capacity to support defence programmes when international supply tightens.
The proposed approach would allow European origin requirements to be incorporated into future tenders and, where possible, running contracts. Defence says exceptions would be necessary where legal obstacles exist or where suppliers use the restrictions to impose unjustified price increases. The policy therefore stops short of an unconditional ban on material from outside Europe.
The measures have been developed with the Dutch ministries responsible for economic affairs and foreign affairs. They form part of a wider attempt to treat selected industrial materials as strategic inputs rather than commodities that can always be replaced by the lowest cost international source.
Super fibres are useful to defence manufacturers because they combine high strength with low weight. Dutch Defence identifies applications in helmets, fragmentation vests, military vehicles, and aircraft, where reduced structural mass can translate into increased endurance or lower fuel consumption. Those characteristics make the material relevant across several equipment categories, allowing a shortage at fibre level to affect manufacturers that otherwise appear to operate in unrelated markets.
The vulnerability is industrial as much as technical. The ministry says European producers face pressure from high energy costs and competition from suppliers outside Europe, including China. Defence demand may require specialised grades, repeatable performance, traceability, and long programme lives, but those requirements do not guarantee that an upstream production line remains commercially viable if wider civilian or international demand moves elsewhere.
That mismatch becomes more important as European governments increase spending on vehicles, aircraft, protective equipment, and other military systems. Larger final assembly orders do not automatically create the raw material and intermediate-product capacity needed to fulfil them. A programme can have factories, skilled workers, and prime contractors available while still being constrained by a comparatively small material bottleneck several tiers further up the supply chain.
The Netherlands is addressing the issue through its Chemistry and Materials for Defence Action Agenda. The super-fibre measures sit alongside similar work on components and semi-finished materials where security of supply is regarded as insufficient. The objective is to improve control over the industrial chain before a shortage reaches the point at which a finished defence programme is delayed.
Innovation funding forms another part of the approach. In July, Defence, the ministry responsible for climate and green growth, and ChemistryNL launched a €3.8 million call intended to encourage public-private research and development. The funding is aimed at strengthening material technology and industrial capability rather than relying solely on purchasing rules to protect existing suppliers.
That distinction is important because origin requirements cannot create competitive capacity by themselves. They can protect demand for a European supplier, but manufacturers still have to control energy use, process yield, quality, capital investment, and production cost. If protected capacity cannot increase output or meet qualification requirements consistently, the bottleneck simply moves from foreign dependence to inadequate domestic supply.
Defence materials also carry qualification implications that make rapid supplier switching difficult. Fibres incorporated into ballistic protection or structural systems are part of an engineered assembly, with their mechanical properties feeding into manufacturing processes, testing, and the certified performance of the finished equipment. Introducing a new supplier can therefore trigger engineering and verification work even when the nominal material specification appears similar.
The willingness to consider changes to existing contracts shows that Dutch Defence regards the issue as more immediate than a long-term industrial policy exercise. Altering sourcing requirements after a programme has entered production would, however, require careful implementation. Suppliers may already have approved international sources, agreed pricing, and established manufacturing routes, while a change could affect cost, schedule, and qualification activity.
The policy also builds on earlier Dutch efforts to retain domestic fibre production. Defence has previously worked with industrial partners on preserving European super-fibre capability and has identified the sector as one of several areas where strategic manufacturing needs protection from external competition.
A further study is examining how the industry can be protected and scaled, with results expected in early 2027. That work should indicate whether the Netherlands intends to rely mainly on procurement conditions or whether additional measures will be used to support plant investment, energy costs, stockholding, or production expansion.
The wider significance is the level at which defence resilience is being examined. Industrial policy often concentrates on prime contractors, final assembly plants, and complete weapon systems because those are the most visible parts of a programme. The Dutch approach moves further upstream towards fibres and semi-finished materials whose absence can stop those same production lines regardless of how much capacity exists at final assembly.
For defence manufacturers, the practical consequence will depend on the wording of future tenders and the treatment of contracts already under way. For policymakers, the harder question is whether European demand is large and predictable enough to sustain the production capacity they want to protect. A sovereign factory is only strategically useful if it can remain economically viable between procurement peaks and expand quickly when demand rises.